Should we use consignment stock from a UK seller?
Consignment stock can suit repeat demand when you can track every withdrawal and agree a workable return route. Compare the cash benefit with storage, reporting and loss exposure, and settle purchase triggers before delivery. Discuss whether this arrangement is available for your products with Cambridge China Bridge.
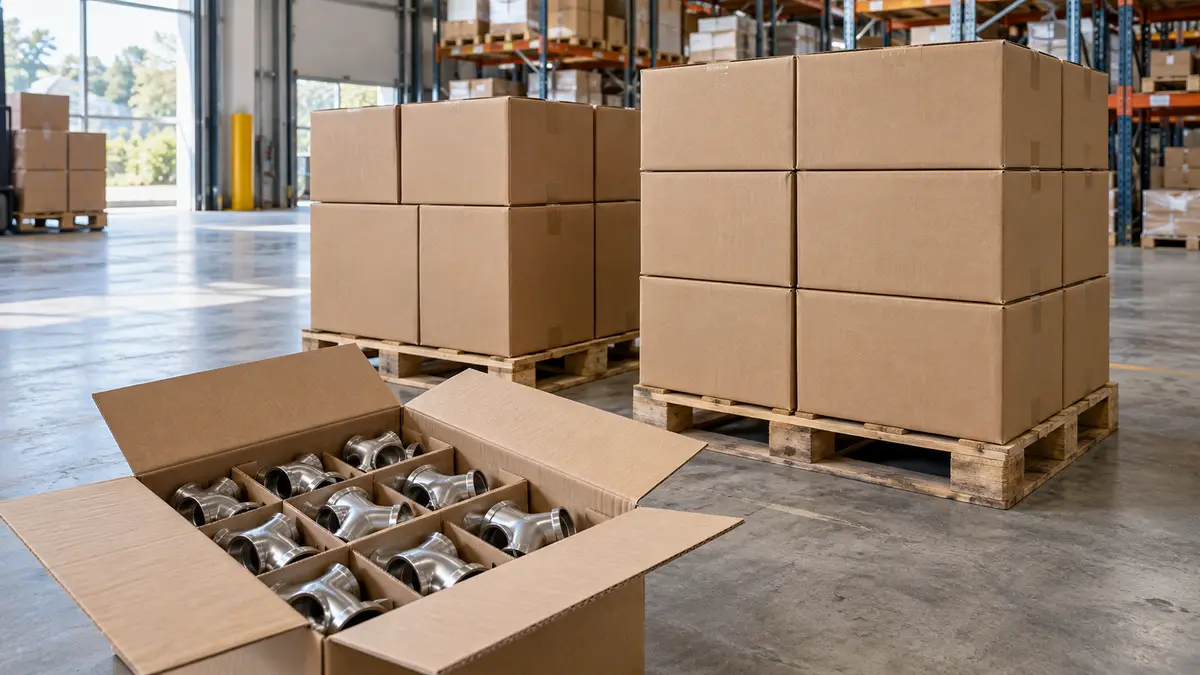
Check the fit and the seller's offer
Consider consignment when you need stock close to production or customers but want to purchase it as it is withdrawn. It is harder to manage where goods are mixed together, modified before recording, perishable or difficult to return. Compare the proposed arrangement with ordinary purchasing using your demand history, storage capacity and working capital planning.
Ask whether the UK sourcing company will sell you the withdrawn goods or act for another seller. Use seller or agent to settle that role. Request a written proposal naming the stock location, permitted users, replenishment method, storage charges and any compulsory purchase of slow-moving stock. Do not assume Cambridge China Bridge offers consignment for every product.
Separate ownership from responsibility for loss
Write down who owns stock while it is stored and exactly when ownership transfers. Define the purchase trigger: withdrawal for production, allocation to a customer, resale or another agreed event. Address opened cartons, samples, scrap and goods incorporated into your products. Avoid wording that leaves delivery, use and payment competing as possible triggers.
Agree separately who bears theft, damage, deterioration and unexplained shortages, and from which handover point. Mark and segregate the seller's stock, record its location and agree access for checks or collection. Have the ownership and recovery wording reviewed before signing, particularly if stock will be mixed or processed. Check it alongside the wider UK seller supply terms.
Make physical counts reconcile with the records
Agree a signed opening count by product, batch, condition and storage location. Record receipts, withdrawals, customer returns, transfers, damaged stock and authorised adjustments separately. Reconcile opening stock plus receipts and returns, less withdrawals and agreed removals, against the closing physical count.
Name who counts, who witnesses and who approves corrections. Agree count frequency, seller access and how movements are paused or captured during a count. Investigate differences before treating them as consumption or billing them. Keep batch identification intact where it supports traceability from factory to customer.
Agree consumption reports and invoice checks
Define consumption using the agreed purchase trigger rather than an unexplained stock decrease. Set a reporting cut-off, submission method and named contacts. Each report should identify the product, batch, quantity, trigger date, agreed price and corrections. Agree how late entries and customer returns are handled, then match invoices to approved reports without concealing disputed movements.
Agree prices, VAT treatment, payment terms and the correction process before stock arrives. HMRC says call-off arrangements that amount to extended credit follow normal VAT tax-point rules; paying as goods are consumed does not automatically defer VAT. Ask your accountant to check the actual terms, including return rights, before relying on the consumption report as the VAT trigger.
Confirm insurance for stock owned by someone else
Give your insurer the proposed arrangement and ask for written confirmation covering stock owned by the seller at the actual premises. Check storage conditions, theft, accidental damage, water damage, deterioration and goods being processed. Agree the insured valuation, excess, exclusions and who pays any uninsured loss.
Allocate cover during delivery, transfers and return transport as well as storage. Name who reports incidents, preserves photographs and stock records, handles the claim and receives settlement. Ask how the seller's interest is recorded and how overlapping policies will be handled. Seller ownership alone is not a useful answer to an insurance question.
Working out your own order? Send us the product on WhatsApp and we reply the same working day: WhatsApp us
Plan unsold goods and the end of the arrangement
Agree which goods can be returned, in what condition and packaging, and whether opened, obsolete or customised goods are excluded. Set the review process for ageing stock, replenishment limits and approval of replacements. Name who pays for collection, repacking and transport, and whether any remaining stock must be purchased.
For termination, agree notice, a final joint count, outstanding consumption reports, invoice reconciliation and a collection appointment. Specify storage arrangements while collection is pending and approval for disposal of damaged goods. Start with a bounded product range and review the count discrepancies, administration and unsold stock before expanding.
Frequently asked questions
Is consignment stock the same as buying on credit?
Check the terms. Ask whether you can return unused goods or must eventually buy them. Agree the ownership and purchase triggers; the label alone does not explain the arrangement.
Who pays for missing consignment stock?
Agree this before delivery. Separate recorded consumption from theft, damage and count errors, and specify who investigates, approves adjustments and bears uninsured losses.
Can we pay VAT only when we use the stock?
Do not assume so. HMRC says call-off arrangements amounting to extended credit follow normal tax-point rules. Ask your accountant to check the actual agreement.
What happens to unsold consignment stock?
Agree return rights, acceptable condition, collection costs and any compulsory purchase before accepting stock. Include a final count and reconciliation when the arrangement ends.